

Hey, Hope you are crushing it this afternoon!
The last few days have been a lot. Good kind of a lot, but still a lot.
Moved apartments. New place, new area, more breathing room, and actually a solid view. Worth it.
But, honestly, it was crazy getting there. Complete chaos. Moving boxes, making sure work doesn’t slip, and trying to keep my brain from short-circuiting all at once.
Body and mind both took a hit, not going to lie.
But we’re settled now. That part’s done.
How are things on your end?
Summer’s creeping in, which means the usual slowdown is coming. Capital raising gets quiet, calendars thin out, and everyone kind of... disappears for a bit. Happens every year.
But absolutely. It doesn’t mean we slow down, though.
Work keeps going regardless of the season. That’s just how it is.
You catch up where you can, you keep moving, and you don’t let the summer lull turn into a full stop.
& By the way, the best thing that happened to me is that I have enrolled myself in a vocal acting studio. Always looking to upscale and build my skill set.
Had the first session this week that lasted for like two hours, and I am already excited for the next one.
Well, let’s move to the deep capital insights that I’m actually seeing right now
Three things happened these past weeks that tell me more about where the market is heading than any trend report I’ve read this quarter.
First, I helped build out a fund vertical focused entirely on optometrists. And the reason that works is the same reason broad theses are dying quietly right now.
LPs are exhausted by “We back healthcare founders.”
They want the person who can tell them exactly why a 3-location optometry practice has been systematically ignored by software and why that gap is now worth capital. Hyper-specificity is not a niche strategy anymore. It is the strategy.
Many founders kind of ignore this space and this backlash.
Second, I sat down with a founder for a portfolio health check, and what came out of it was blunt. Some bets are holding, while some have already told us what our thesis got wrong. That line stuck with me because it is true, and most people in this space are not honest enough to say it out loud.
The market has shifted in the last 12 to 18 months in ways that looked subtle at the time and are now impossible to ignore.
Founders who were raised on assumptions from late 2024 are operating on outdated maps. I see this every week.
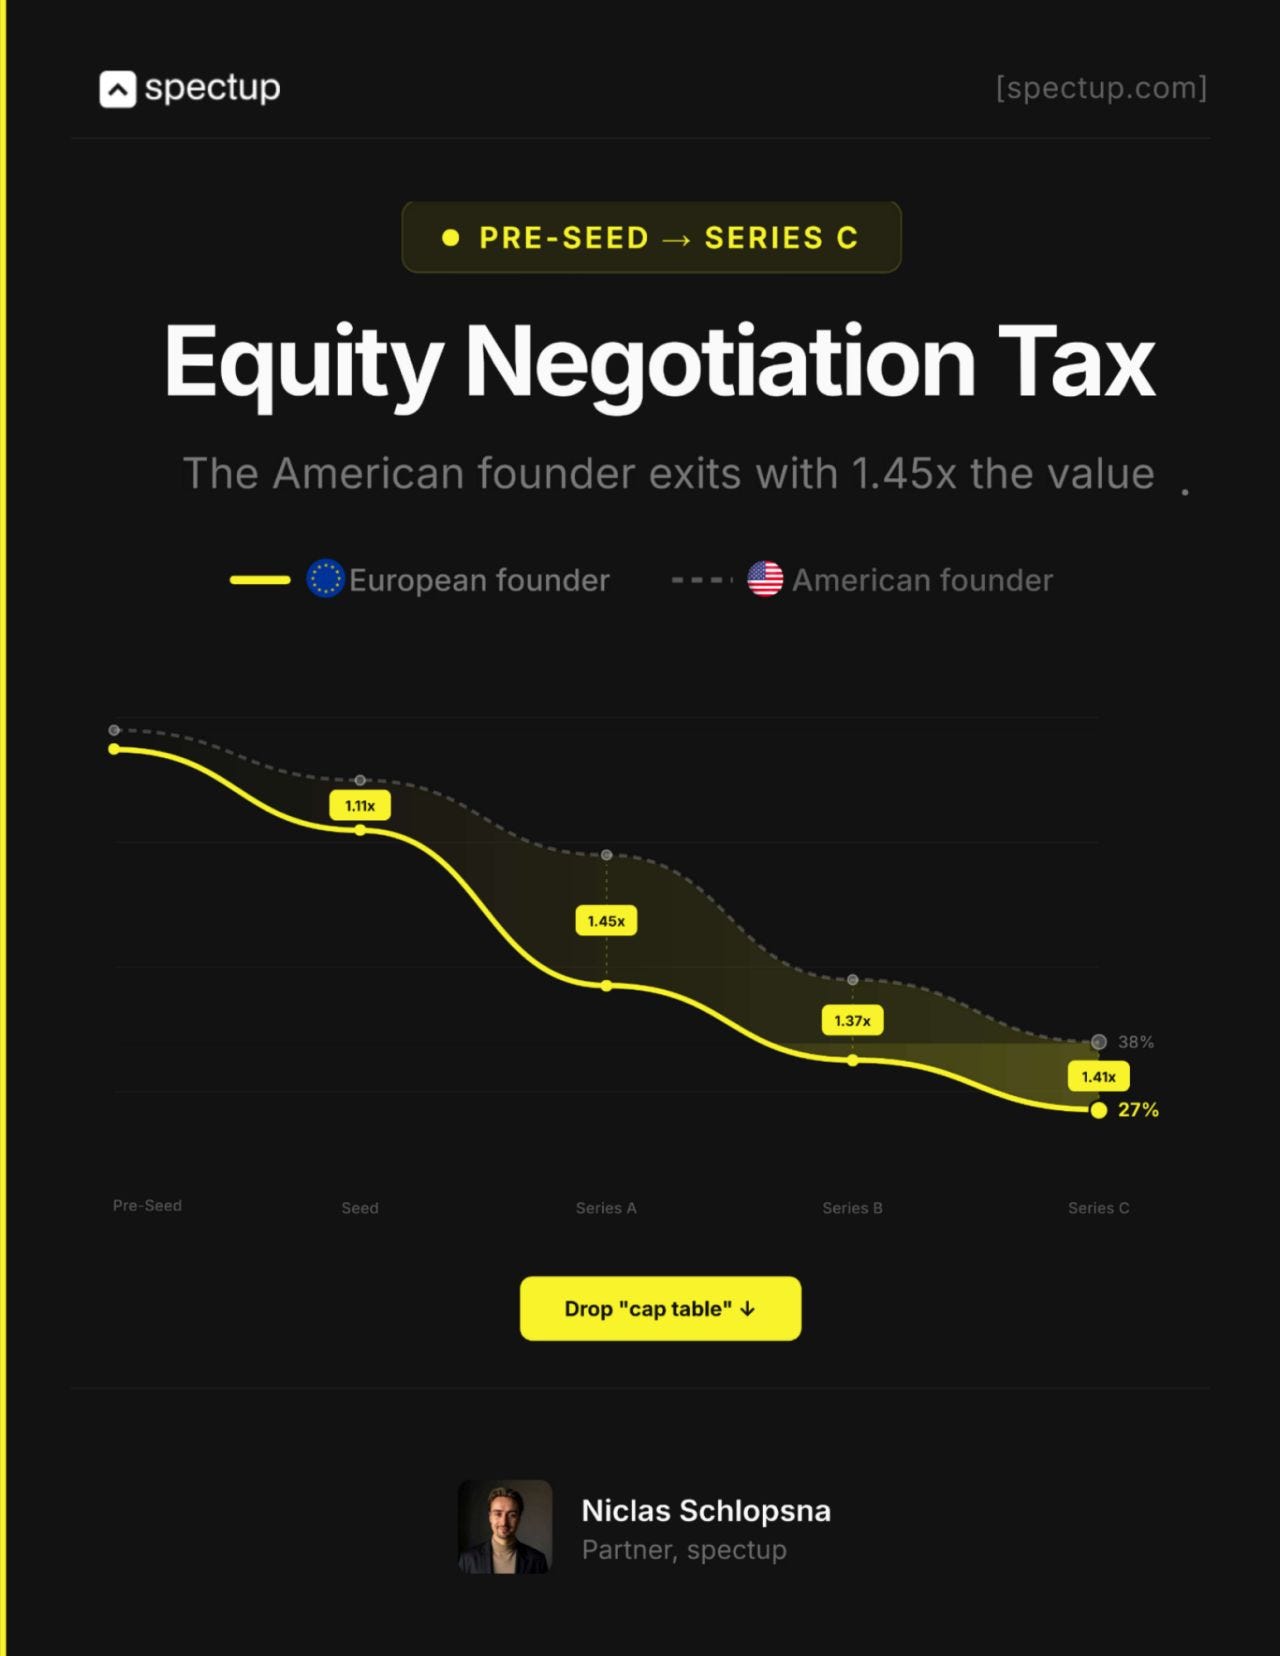
Third, I had to sit with my team twice in 24 hours. Now, it might look weird to you, but we usually operate in a way that keeps the work divided in a more synchronised way.
Anyways, I had to get back to a call with the team. Once for Series A prep and the second time because investor conversations had cracked open something he hadn’t anticipated.
Investors are no longer accepting “we execute better” as some kind of unique excellence. That answer is dead.
What they want now is network ownership, structural lock-in, and something that makes your position genuinely difficult to replicate.
Again, if any founder were to come to me and ask me to hand over secret sauce to him, I would say,
‘Execution is the floor, and defensibility is the ceiling. And the gap between knowing that intellectually and being able to articulate it in a room with investors? That gap is costing founders real money right now.’
This is what May 2026 looks like from inside the work. And to be very fair, this is how I am looking at things. Very closely and with a deep dive.
Now, when all these signals are there, very naturally we all think, ‘What about the startups raising capital?’
Is Europe back on track?
Or is the US still holding that top space?
Everyone asks me this, and right now the honest answer is complicated.
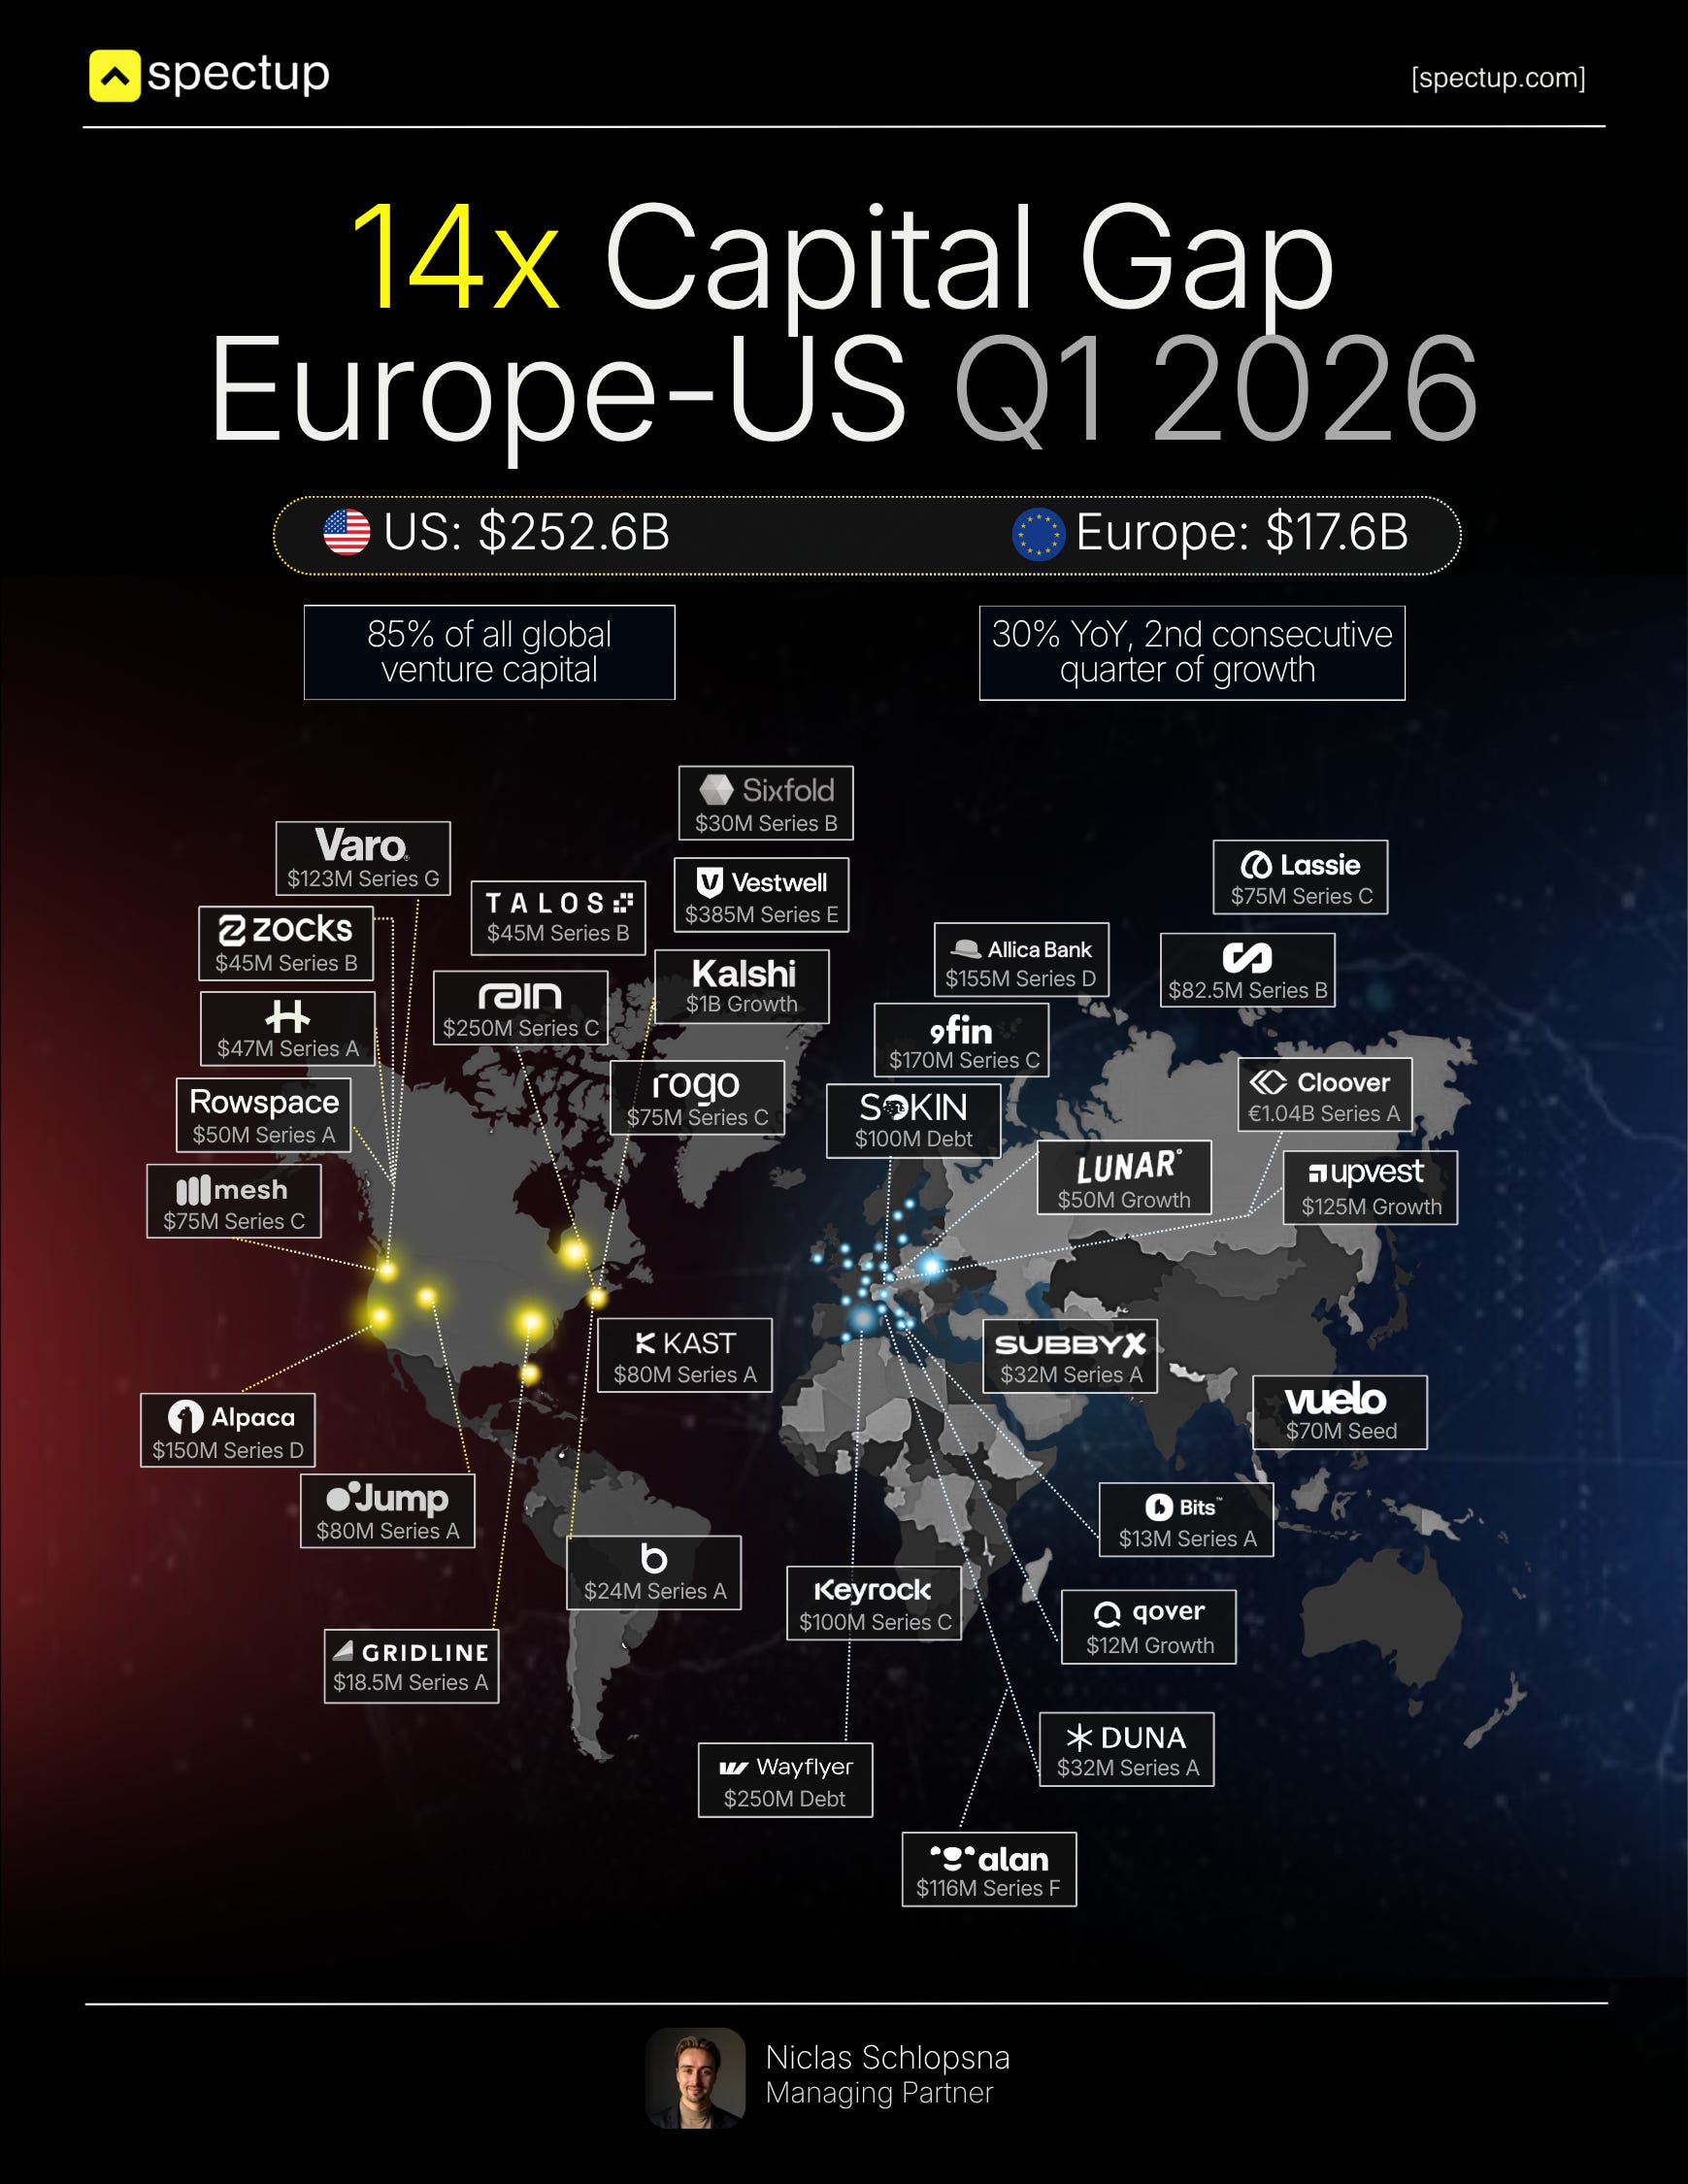
European startups raised $17.6B in Q1 2026. Up 30% year over year. On paper that sounds like a comeback story.
Like Europe is finally hitting its stride, and the ecosystem is maturing the way people have been predicting for years.
I don’t fully buy it.
Here is what that number does not tell you.
At Series B, Europe is sitting on a $13.5B funding gap versus the US.
Seed is fine.
Early stage is moving.
The moment a company needs to scale seriously, the capital dries up, or it comes from across the Atlantic with strings attached.
And then there is Lilium.
Germany’s government was asked for a EUR 100M bridge loan guarantee. One hundred million euros to keep a decade of German aerospace innovation alive. They said no, and the company went insolvent.
A California competitor walked in and bought 300 patents for EUR 18M. Eighteen million.
I have heard people call Lilium an outlier. I think it is the cleanest example of a systemic pattern that plays out again and again.
European founders build for a decade. Non-European capital funds the journey. Then at the exact moment commercialisation requires government confidence, governments blink. And US competitors pick up the pieces for almost nothing.
The 30% funding increase is real. But it is masking a structural problem at the growth stage that no quarterly number is going to fix on its own. The gap at Series B is built into how Europe thinks about risk at the critical moment.
This is the exact gap spectup works in daily – the brutal middle, where European founders are technically ready and commercially viable but cannot find the capital their own governments won’t back.
And finally, finally, I can reveal it.
In the last newsletter I revealed this as well, but in case you missed it, I am adding it here again.
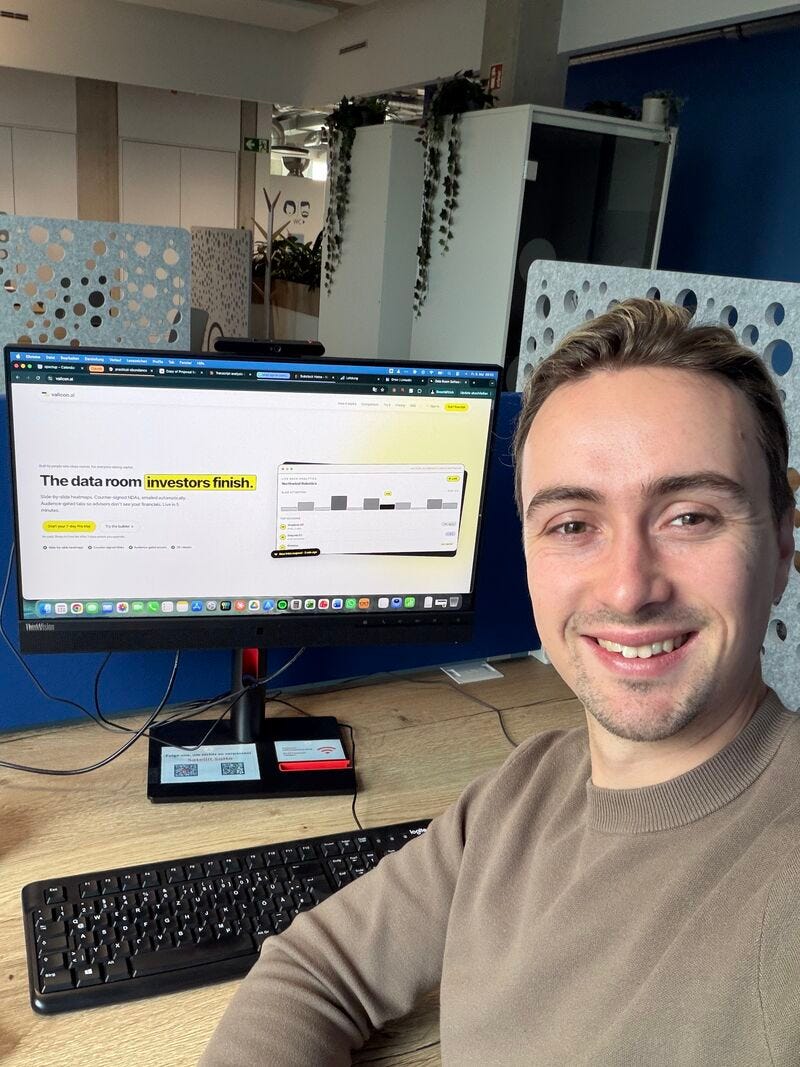
We built Valicon.ai, our own data room software that does not just tell you the link was opened; it shows you much, much more. Like:
Slide-level heatmaps
Dwell time on every block
Forward detection
Investor radar
The whole picture of what actually happens inside your room.
Four weeks of nights and weekends, and honestly, the most useful thing we have shipped at spectup in three years. It is live right now, and I cannot wait to see what you think.
That’s it from my end for this one.
Genuinely curious how things are looking on your side. Is the summer slowdown hitting you yet, or are you still in full sprint mode?
Hit me back, DM me, reply to this, or whatever works. I read everything. If you get a response fast, that’s just me!
One thing I’ll leave you with: the Series B gap conversation is not over. I have more thoughts on what European founders should actually be doing differently right now, and I’ll keep sharing things, and hopefully, you won’t get bored.
Stay sharp.
Ta-da!!!!
About spectup:
Capital advisory for companies raising from institutional investors (family office, VC, private equity) and for GPs raising a new fund and need intros to Limited partners